Executive Summary
- I believe that plan governance qualifies as an investment variable. It defines the objectives, decision rights, delegation, risk limits and accountability that determine how integrated—and effective—a total portfolio can become.
- Governance is also essential to employing a Total Portfolio Approach (TPA) and the Integrated Capital Framework (ICF) to create a common framework for investing across public and private assets.
- Investment-specific governance remains relevant but, in my view, is secondary to plan governance. It captures the incremental underwriting, implementation and monitoring burden created by a mandate and should be evaluated as one portfolio attribute within ICF.
Introduction: New Focus on Governance Amid Portfolio Integration
In my view, plan governance is more than an overall architecture for investment portfolios; it can also be an investment variable. It determines the fund’s objectives, who may act, within what limits, on what information and with what accountability. Those choices define the feasible investment set, the speed and quality of implementation and the practical form of a Total Portfolio Approach (TPA).
Governance models may differ, but the central issue for many institutions is remarkably consistent: They want governance to facilitate a more integrated view of risk and opportunity while preserving the accountability that their boards, beneficiaries and regulators require.
This article applies the idea of an integrated governance framework to TPA and the Integrated Capital Framework (ICF), which I have discussed in previous writings.1
Current Portfolio Frameworks
Total Portfolio Approach. TPA is a holistic portfolio mindset and operating model. It manages the portfolio as one system and judges each decision by its contribution to the total fund. TPA can enhance rather than replace strategic asset allocation (SAA) consistent with regulation, governance and/or expected-return accountability; its practical form must follow the institution’s governance structure.
Integrated Capital Framework. ICF is the shared analytical framework that applies the TPA mindset across asset types. It moves beyond asset-class labels to focus on an investment’s economic characteristics, risks and impact on the existing portfolio. It compares marginal public and private investments through common dimensions such as expected return, total-portfolio risk, factor exposure, liquidity, convexity, implementation cost and governance burden. Over longer-term horizons, the returns of both public and private assets will generally be correlated with outcomes in the real economy, including growth, productivity, inflation, government spending and private capital flows. ICF makes those common economic linkages more visible for long-term investors.
A Less Divided World: Risk and Portfolio Systems Work Across Public and Private Asset Classes
Public and private markets have often operated as separate worlds, where distinct investment and research staffs apply distinct portfolio measures and systems to evaluate, select and monitor investments and portfolio allocations.
Today, this division is being addressed in complementary ways.
First, private-asset data and analytics are being incorporated into established enterprise risk and portfolio systems. MSCI BarraOne supports risk analysis across public and private assets, complemented by MSCI’s Burgiss private-capital data and analytics. BlackRock is integrating Preqin data and analytics into its private-markets technology ecosystem, including eFront Insight within the broader Aladdin platform. SimCorp One likewise presents public and private positions through a unified data and analytics foundation.
Second, AI-assisted Python applications and scripts can draw from these systems and other portfolio data sources, select the appropriate level of detail and customize factor, sector, liquidity and risk views for the institution’s specific TPA and ICF questions. These developments do not eliminate valuation lags, data limitations or modeling judgment, but they can materially improve portfolio visibility and make a common total-portfolio view increasingly feasible.
Correctly applied, these advances can meaningfully enhance governance across asset classes, but care is required: Differences among public pensions, sovereign institutions, insurers, endowments, foundations, corporate plans and superannuation, for example, mean that the task is not as simple as simply copying a given model. Institutions with similar liabilities and return objectives can rationally hold different portfolios because their governance capacity differs, while board authority, professional delegation, information systems and monitoring resources each affect what the institution can responsibly own and how quickly it can act. The table below outlines how various institutions can think about the alignment of their governance priorities and portfolio integration.
Alignment of Institution Governance and Portfolio Integration Frameworks
| Institution | Governance Context | Practical Implication |
|---|---|---|
| Public Pension | Statutory authority, public process and stakeholder visibility | ICF can integrate decisions within SAA; purer TPA requires clear delegation |
| Corporate Plan | Funded status, sponsor balance sheet, accounting and transfer objectives | Whole portfolio decisions should connect growth and liability hedging |
| Sovereign or Reserve | Potentially broad delegation with national, currency or reserve constraints | TPA can work well when mandate and accountability are explicit |
| Insurance Company | Capital charges, accounting, ratings and asset liability requirements | ICF should treat capital use and liability fit as explicit attributes |
| Endowment or Foundation | Broad discretion but widely varying staff and board capacity | Liquidity and governance may define how far integration can extend |
| Superannuation or Defined Contribution | Member outcomes, regulation, product design and operating scale | TPA can work at pooled fund level within liquidity and product limits |
Central Design Question: How to Align With Investment Mandates
Different governance structures can support different flavors of TPA. Some structures—with broader professional delegation, stronger analytical resources and clearer total-fund accountability—may be more supportive of the operating model than others. But a less delegated structure does not necessarily invalidate a move toward a more holistic mindset or greater quantitative and analytical rigor. Where boards retain allocation authority, ICF can improve comparison and portfolio coherence within an SAA. Where boards delegate implementation within a clear risk contract, a more fully expressed TPA becomes possible.
As one would expect, adjustments to governance may sometimes be needed to achieve the optimal framing and results from TPA. Boards should define objectives, risk tolerance, decision rights and delegation boundaries, while reporting and incentives should reinforce total-fund accountability rather than competition among sleeves. However, adopting TPA and ICF does not require a board to cede investment decision rights or control to the investment team. A board may retain those rights and still benefit from a more holistic portfolio mindset, consistent analytical comparisons and stronger quantitative rigor. The transition can be challenging for a lay board when the discussion becomes more quantitative and risk-oriented. Investment professionals therefore also become storytellers: We must translate factor exposures, risk budgets, correlations and scenarios into clear narratives that trustees can understand, challenge and ultimately support.
Drilling Down: Plan Governance as Architecture for Portfolio Integration
Plan governance may be regarded as the institutional architecture that converts fiduciary duty into an investable operating model. It establishes objectives and risk tolerance, assigns decision rights, sets delegation boundaries and determines how performance and risk are reported and reviewed. Those choices define the feasible investment set and the practical form of TPA.
A well-designed structure does not require trustees to manage individual investments. It allows them to set the mandate, approve the risk contract, ensure that staff and systems are capable and hold the organization accountable for total-fund outcomes. Staff then acts within explicit limits, with transparent reporting and clear escalation when an exception crosses those limits. The conceptual progression of these elements is shown below.
The Plan Governance Chain
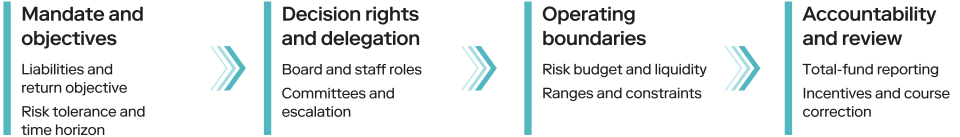
The strength of the plan governance chain determines how far integration can extend. Where boards retain substantial allocation authority, ICF can improve comparison and portfolio coherence within an SAA construct. Where boards delegate implementation within a clear total-fund risk contract, a more fully expressed TPA becomes possible.
Plan Governance and Investment-Specific Governance
The distinction of plan versus investment-specific governance is important. Plan governance covers the institution and the total fund; it is the architecture for the entire enterprise. Investment-specific governance is narrower; it is the incremental work and capacity created by a particular mandate. It should inform investment selection without displacing the plan-level decisions that determine what the institution can responsibly own in the first place.
Plan vs. Investment: Key Differences in Emphasis
| Governance Level | Primary Question | Core Elements | Portfolio Role |
|---|---|---|---|
| Plan governance | How does the institution govern the total fund? | Mandate, objectives, decision rights, delegation, risk limits, reporting and accountability | Defines the feasible investment set and the practical form of TPA |
| Investment-specific governance | What incremental work does this mandate require? | Underwriting, terms, implementation, data, monitoring, conflicts, remediation and exit | An ICF attribute affecting governance-adjusted value |
Private equity illustrates the narrower, investment-specific meaning of governance. For example, a PE mandate may require incremental underwriting, legal negotiation, data integration, performance and risk monitoring, conflict management, remediation and exit planning. Within ICF, that burden is one attribute of the investment and one component of the institution’s illiquidity requirement; it is not the organizing thesis of the plan’s governance model. Higher levels of asset-specific governance requirements reduce an investment’s relative value unless its expected contribution to the portfolio adequately compensates the institution for that additional burden.
Building Governance Capacity Through Partnership
Plan-level capacity can be strengthened through clearer delegation, reusable diligence modules, standing legal terms, common data definitions, preapproved ranges and exception-based reporting. Capable partners can add comparable public/private analytics, liquidity analysis and implementation alternatives without lowering fiduciary standards.
I believe clients will increasingly require analytical support as they build out their capabilities and refine their approaches to TPA and ICF. Asset managers should be able to help institutions compare public and private opportunities within a unified portfolio context, develop customized investment solutions and evaluate how implementation choices affect overall portfolio positioning. The objective should not just be to provide more analysis, but to translate better information into practical decisions that can strengthen resilience and performance across market cycles and risk regimes.
Conclusion: The Central Role of Governance
TPA is not new. Leading institutions have shown for nearly 20 years that professional delegation and integrated risk management can support a total-fund objective. Different governance structures will produce different flavors of TPA, but every institution can move toward a more holistic mindset and greater quantitative and analytical rigor. ICF provides the common analytical language, while plan governance determines how fully the institution can act on it.
Investment-specific governance remains important, particularly in private markets, but it is subordinate to the plan-level architecture. The mandate creates incremental ownership demands; the board determines whether authority, capacity and accountability exist to meet them.
Based on observations across multiple market cycles and risk regimes, I believe the institutions that make the most progress will combine a better operating model with disciplined implementation. Asset managers can do their part by delivering standalone public and private mandates, investment opportunities that span both asset types and implementation advice on customized solutions—always with a clear view of how each decision can improve overall portfolio positioning, resilience and long-term performance. As portfolios become more customized, analytical and integrated, governance becomes more consequential, not less. The portfolio cannot be more integrated than the governance supporting it.
About the Author
Steven Meier is Vice Chair of the Institutional Client Group and a member of Neuberger’s Asset Allocation Committee and Public–Private Investment Committee. He has more than 40 years of global investment experience, previously holding senior roles at State Street Global Advisors, Credit Suisse First Boston, Oppenheimer Capital and Merrill Lynch. Steven has also served as Chief Investment Officer of the New York City Retirement Systems and as Interim CIO for the State of Connecticut’s public pension plans. This article builds on Steven’s continuing dialogue with institutional investors on a global basis, sharing perspectives, ideas and innovations to foster effective solutions to their long-term investment challenges.