Corporate fundamentals have been broadly strengthening: The median stock—including small caps, mid caps and large caps—has seen steady improvement in EPS growth.
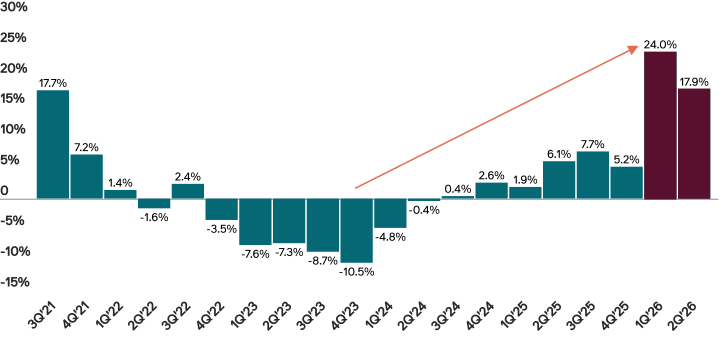
Russell 3000 Median Stock EPS Growth (y/y)
Equities: Hope for a genuine broadening.
- As shown in the chart, the median stock in the Russell 3000 Index has now posted eight consecutive quarters of improving EPS growth, climbing from a sub -10% trough in 4Q'23 to an estimated +24% in 1Q'26. This tells us the recovery is no longer concentrated in a handful of hyperscalers and megacap stocks; it's an improving corporate fundamentals picture across the entire market-cap spectrum.
- This earnings strength underpins resilience equity markets have demonstrated across 2026 in the face of an energy price shock and a sharp repricing of the interest rates to sit near all-time highs. In fact, S&P 500 consensus EPS growth for 2026 has been revised up to over 22% (from ~15% at year-end), with eight of twelve sectors carrying both double-digit earnings growth and positive revisions. Energy and Technology are doing the heaviest lifting on revisions since the conflict began, but the breadth underneath, within Materials, Communication Services, Industrials, Financials, supports the broadening out thesis.
Credit: Fundamentals justify the tightness.
- The same story is anchoring spreads across the corporate credit complex. Though credit spreads remain at historically tight levels by any measure, but the fundamental justify persistence, underpinned by solid corporate balance sheets. In high yield, the market looks to be structurally healthier with BB-rated names now representing more than 60% of the index1 and default expectations sitting well below 2% for both 2026-2027. Combined with higher base rates, all-in yields across the credit spectrum look attractive relative to recent history.
Neuberger Investment View.
- The key takeaway for investors is earnings expectations, not headlines, are driving this market, and the credit complex is corroborating the equity signal. For now, we advocate taking a long-term view: overweight global equities; whilst positioning for clearest earnings delivery across US and non-US markets, paired with carry-focused fixed income exposure diversified across the credit quality spectrum.
Source: Neuberger research and FactSet. Data as of May 15, 2026. Past performance is not indicative of future results.
1. ICE BoA Global High Yield Index.