Commentary
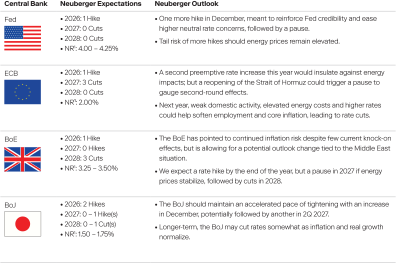
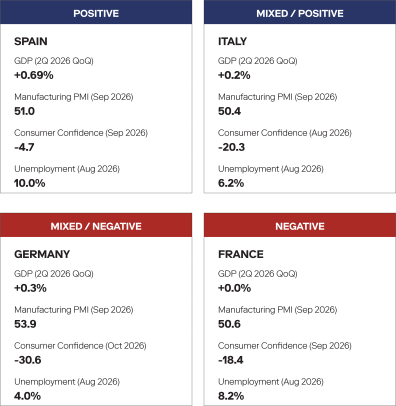
The fixed income environment has been particularly painful for investors in recent months, as long-term yields increased to multiyear highs amid geopolitical and economic turbulence. Slow progress on inflation, energy shocks and heavy issuance were among the headwinds, along with a hawkish turn by central banks. In the U.S., economic growth remained stable and wage pressures contained, while Europe maintained lower but still resilient growth in the face of high energy prices. Credit spreads remained tight but showed signs of widening amid strains to business models.
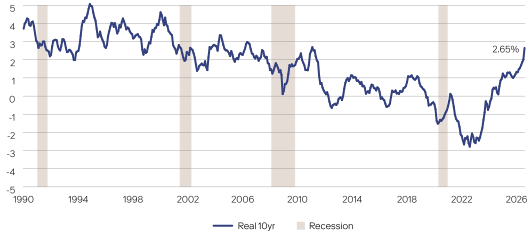
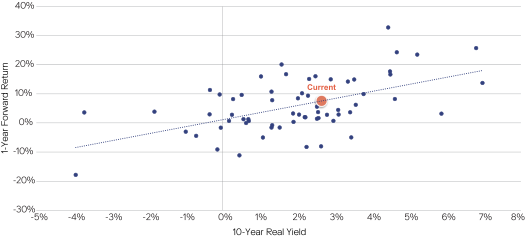
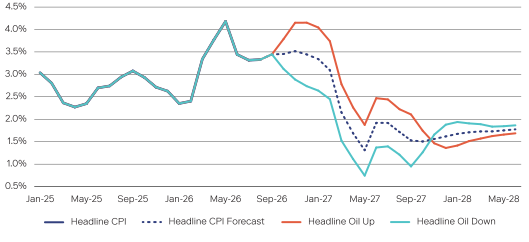
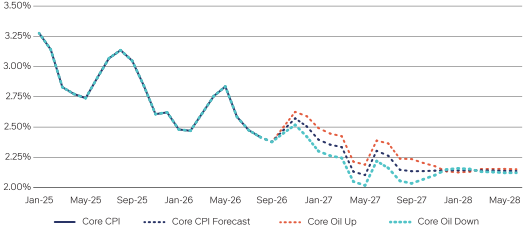
Looking ahead, we believe that markets may be overestimating the extent of central bank tightening, given the relatively modest contagion of energy costs to other areas of the economy and otherwise continued progress on core inflation. In addition, we think higher real yields generally are raising the value profile of the market without yet reaching destructive levels.
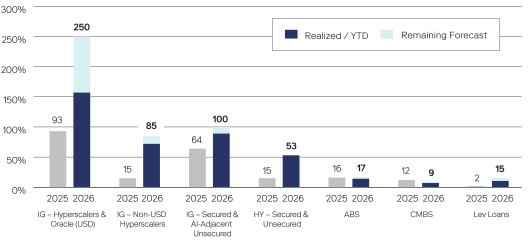
From a positioning perspective, we favor capturing duration opportunities at the short to medium sections of the yield curve. Even amid central bank rate hikes, varying fundamental paths across and within geographic regions provide diversification and incremental income potential. Within credit, we believe that yields on hyperscaler issuance are attractive, including at longer maturities; and we favor select areas, such as securitized, that are supported by economic stability and provide a favorable yield/duration balance. That said, we have become more cautious on credit generally, believing that the turbulence experienced by rate markets may spread to other areas.
We present our current investment themes on the pages that follow.